Inside the Memory Supercycle Powering Micron Stock
Memory chips run the digital world, but their prices swing like agricultural commodities. Here is how AI data centers and HBM packaging transformed the classic memory cycle.
When I examine semiconductor earnings reports, Micron Technology always stands apart from designer chipmakers like Nvidia or Apple. Micron does not merely write software code or design abstract circuit blueprints. It operates colossal, multi-billion-dollar fabrication plants that churn out billions of microscopic memory chips every single week. Yet for decades, Wall Street treated memory chips almost like wheat, pork bellies, or crude oil. Memory was a brutal commodity business defined by dramatic boom-and-bust cycles. When demand surged, memory prices skyrocketed and profits exploded. But whenever chipmakers built too many factories, excess supply flooded the market, prices collapsed, and share prices cratered.
That historical roller coaster explains why Micron stock has experienced such breathtaking swings across market history. When we track the stock ticker over multi-year periods, the volatility looks staggering. Investors often struggle to understand why a company with cutting-edge technology can see its profits plunge into deep losses during an industry downturn, only to rebound with record windfalls two years later. To understand Micron, you must understand the unique mechanics of the semiconductor memory cycle.
The Anatomy of a Semiconductor Boom and Bust
The memory cycle is driven by a fundamental physical reality: building a modern semiconductor fabrication plant requires staggering amounts of capital and years of lead time. You cannot spin up a new memory cleanroom overnight. An advanced fabrication facility costs between fifteen and twenty billion dollars to construct and equip with extreme ultraviolet lithography machines.
Because factory construction takes two to three years, memory manufacturers must guess what global demand will look like far in advance. When smartphones, personal computers, or enterprise cloud servers suddenly demand more memory, manufacturers cannot immediately open extra production lines. Supply stays tight. Memory prices rise quickly. Seeing surging prices and fat profit margins, every major memory producer greenlights massive capital expenditure budgets to expand fabrication capacity.
A classic trap follows. Years later, those newly built multi-billion-dollar cleanrooms all begin pumping out silicon wafers at the exact same moment. If consumer electronics demand slows down just as all that new capacity arrives, an enormous supply glut materializes. Because cleanrooms have immense fixed depreciation costs, running a factory at partial capacity is economically painful. Producers keep running their lines, slashing spot prices to move inventory. Spot memory prices can drop fifty percent in a matter of months, dragging corporate earnings into the red.
From an Idaho Dental Office to Global Memory Leader
Micron's corporate survival across these savage cycles is one of the most charming underdog stories in American technology. In October 1978, four engineers founded Micron in the basement of a dental office in Boise, Idaho. Ward Parkinson, his twin brother Joe Parkinson, Dennis Wilson, and Doug Pitman began with a modest consulting contract. When they decided to manufacture DRAM chips themselves, they secured crucial early backing from legendary Idaho potato billionaire J.R. Simplot. Simplot recognized raw ambition and bankrolled their first fabrication facility among the Boise potato fields.
During the mid-1980s, dozens of American semiconductor pioneers collapsed under intense global price wars. Micron survived through relentless cost discipline, innovative chip layouts, and sheer operational grit. By staying nimble, the Boise company outlasted domestic competitors to become the only major US-based manufacturer of dynamic random-access memory. I find that historical resilience deeply inspiring.
How Artificial Intelligence Altered the Classic Equation
For forty years, standard dynamic RAM (DRAM) and NAND flash storage chips drove the memory market. Every personal computer and smartphone needed standard memory sticks and solid-state drives. But the sudden explosion of generative artificial intelligence created a whole new category of demand: High Bandwidth Memory, known throughout the industry as HBM.
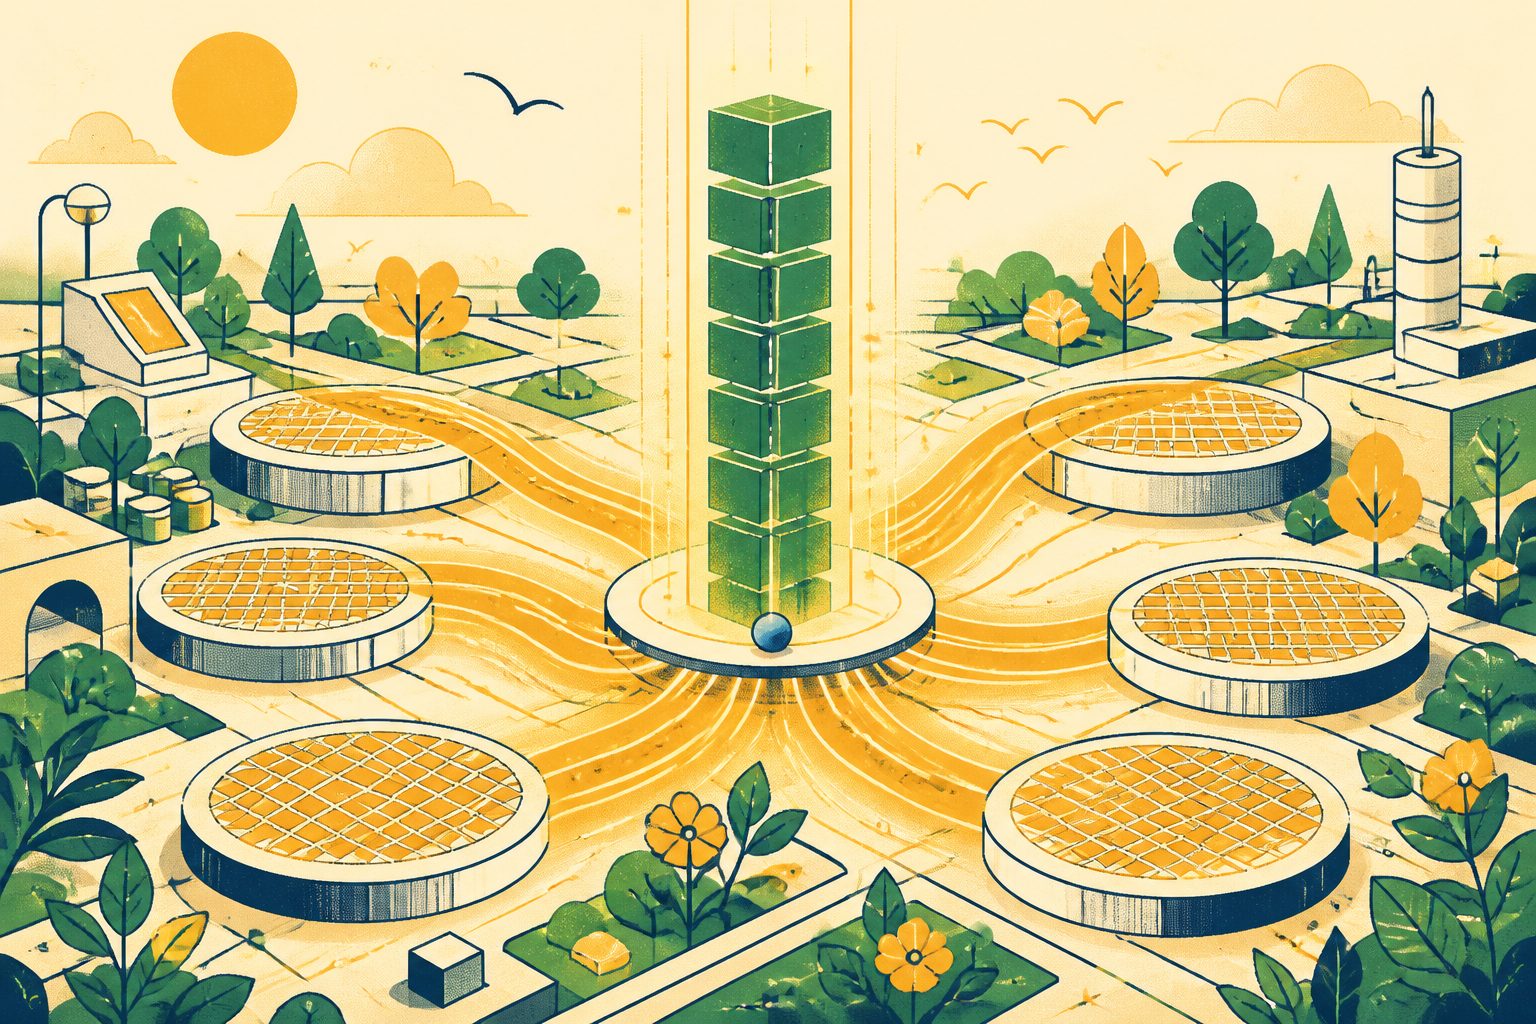
Artificial intelligence accelerators require immense computational throughput. Massive graphics processor clusters cannot train advanced neural networks if they spend precious milliseconds waiting for data to travel across a circuit board. HBM solves this bottleneck by stacking multiple DRAM dies directly on top of each other using microscopic through-silicon vias. The stacked cube is then mounted directly alongside the computing processor on a shared silicon interposer.
We are witnessing a structural transformation in how memory is purchased. Standard commodity DRAM was sold on open spot markets with fluctuating daily prices. In contrast, advanced HBM3E memory requires bespoke packaging, custom qualification with chip designers, and long-term customer commitments. In SEC filings and investor briefings leading into autumn 2026, Micron reported that its advanced HBM capacity was fully booked out through calendar year 2027 under multi-year agreements.
Key Drivers Shaping Micron's Business Model
When assessing Micron stock over a multi-year horizon, several distinct technological and financial pillars govern its performance.
Micron Business and Market Dynamics
- Founding Year
- October 1978 in Boise, Idaho
- Core Product Lines
- DRAM, NAND Flash, and HBM3E Memory Stacks
- Cleanroom Construction Cost
- $15 billion to $20 billion per advanced fab
- Fabrication Lead Time
- 18 to 36 months from groundbreak to full wafer output
- HBM Wafer Consumption
- Roughly 3x the wafer area of standard commodity DRAM
- Contract Structure Shift
- Transition from spot commodity pricing to multi-year supply agreements
An intriguing dynamic of HBM manufacturing is its wafer penalty. Producing one gigabyte of HBM3E memory consumes roughly three times the raw silicon wafer capacity of standard DDR5 computer memory. Because manufacturing HBM requires extra wafer space for through-silicon vias and complex testing, allocating cleanroom capacity to AI memory naturally restricts the supply of standard PC and smartphone memory. That supply tightening supports broader pricing across ordinary consumer categories.
What Everyday Investors Should Keep in Mind
Does this mean the classic memory cycle has vanished forever? I do not believe so. Semiconductor physics and market dynamics always reassert themselves eventually. As manufacturers invest tens of billions of dollars into next-generation HBM4 packaging and expanded cleanrooms across the globe, supply will eventually catch up with artificial intelligence demand.
The critical takeaway for everyday investors is that Micron is not an ordinary software company with steady recurring subscription fees. It is an industrial powerhouse operating at the bleeding edge of atomic-scale physics. In our view at Joyful Take, understanding that underlying rhythm turns an intimidating, volatile stock into a fascinating window on global technological progress.
Sources
Every factual claim above traces to one of these. Links open in a new tab.
- Micron Delivers Industry-Leading HBM3E 12-High 36GB Memory
- Micron Technology Form 10-K Annual Report Filings
- Micron Technology Inc. (MU) Stock Price, Quote and Market Valuation
- Memory Chip Dynamics and Capital Spending Cycles
- Micron and the AI Memory Landscape Analysis
- State of the U.S. Semiconductor Industry Report
- Global Semiconductor Manufacturing and Memory Infrastructure
- Micron Technology Company Overview and Market Data